Welcome to this week’s edition of The Weekly Call, your trusted source for high-quality commodity setups and trading strategies. Since October 2016, our approach has delivered an impressive 777% return, and we continue to share the insights and methodologies that drive these results with this post #531. This week, we’ll explore the latest market trends, actionable trade setups, and global economic factors influencing commodities like sugar, coffee, live cattle, and gold.
Financial markets experienced a significant shift this week as investors reduced exposure to technology and artificial intelligence stocks while rotating into defensive sectors.
The Nasdaq declined nearly 4.5%, semiconductor stocks fell more than 11%, and concerns about debt-financed AI infrastructure projects intensified. Meanwhile, the Dow finished modestly higher, suggesting investors are becoming more selective rather than abandoning equities.
Inflation also returned to the forefront. Consumer prices rose 3.7% annually, producer prices increased 6.3%, and WTI crude climbed above $100 per barrel.
The key question is whether this correction represents a temporary valuation adjustment or the beginning of a broader market decline. Upcoming corporate earnings should provide greater clarity.
U.S. Markets
S&P 500: 7,623.68 — down 0.47% for the week
The S&P 500 finished approximately 2.5% below its October 6 record close. Technology weakness and energy prices remain concerns, although the index is still up approximately 11.4% for the year.
I am watching 7,600 for support and 7,800 as an important recovery level.
Nasdaq Composite: 25,955.34 — down 0.71%
AI infrastructure financing remains the principal concern for technology investors.
Meta’s earnings and capital spending outlook contributed to renewed selling, while semiconductor equipment companies also experienced pressure.
The next test comes from Microsoft, Alphabet, and Amazon. Strong cloud revenue and improving AI economics could help stabilize the sector.
Dow Jones Industrial Average: 52,215.16 — up 0.41%
The Dow continued to outperform technology-heavy indexes as investors favored established industrial, energy, healthcare, and defensive companies.
This rotation could continue if financing costs remain elevated.
Russell 2000: 2,775.90 — up approximately 2.0%
Small-cap stocks recovered during the week, an encouraging indication of improving market participation.
However, smaller companies remain particularly sensitive to interest rates and economic conditions.
10-Year Treasury Yield: approximately 4.99%
Treasury yields declined during the week despite a Friday rebound, reflecting continued demand for safer investments.
VIX: approximately 19.5
Volatility remains elevated compared with early October, indicating continued uncertainty about earnings, inflation, and monetary policy.
Global Markets
FTSE 100: 10,690.36 — down 1.76%
British equities weakened as investors assessed growth, inflation, and corporate earnings.
DAX: 25,181.65 — down 1.72%
German equities declined amid concerns about industrial activity and elevated energy costs.
Nikkei 225: 62,693.16 — down 4.03%
Japanese equities experienced substantial selling as global technology-sector weakness spread into Asian markets.
Shanghai Composite: 3,690.48 — down 0.69%
Chinese equities remained under pressure as investors evaluated economic growth and global trade uncertainty.
International markets generally weakened, reinforcing the importance of diversification and selective investing.
Commodities Snapshot
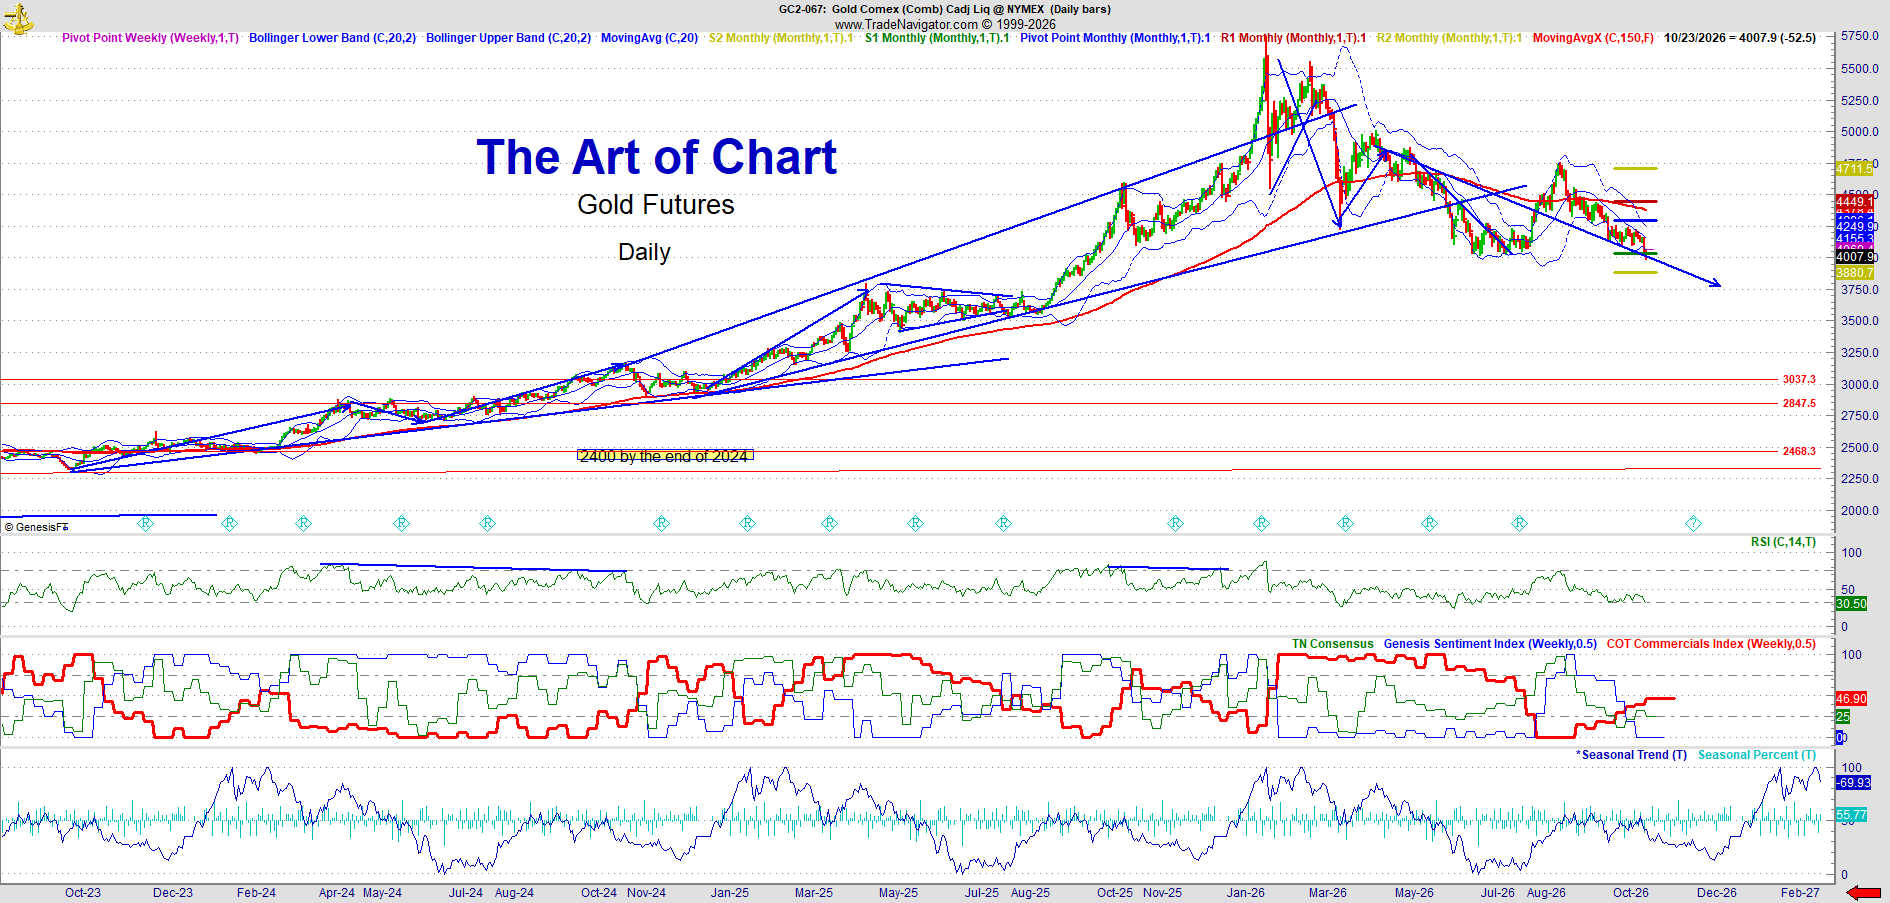
Gold: $4,007.90 per ounce — December futures
Gold declined approximately 4.1% for the week. I am watching the $4,000 level for support and $4,100–$4,200 for recovery.
Silver: $53.95 per ounce — December futures
Silver declined as precious metals weakened. The immediate reference levels are $52 on the downside and $56–$58 on the upside.
Copper: $6.4975 per pound — December futures
Copper weakened during the week, although long-term demand from electrical infrastructure, grid expansion, and data centers remains attractive.
WTI Crude Oil: $103.27 per barrel — December futures
Brent Crude Oil: $116.72 per barrel — December futures
Oil prices increased sharply Friday as attacks affecting Middle Eastern energy infrastructure and shipping intensified supply concerns.
Elevated crude prices create additional risks for inflation, transportation costs, and corporate margins.
Natural Gas: $3.050 per MMBtu — December futures
Natural gas remained softer, with weather, storage inventories, LNG exports, and domestic production influencing prices.
Cryptocurrency Market
Cryptocurrencies remained cautious, with Bitcoin holding near $80,000 while most major altcoins continued to struggle.
| Cryptocurrency | Approximate Price | Change Since Oct. 17 |
|---|---|---|
| Bitcoin (BTC) | $80,525 | -1.2% |
| Ethereum (ETH) | $2,340 | -3.8% |
| Solana (SOL) | $101.27 | -3.1% |
| XRP | $1.30 | -0.8% |
| BNB | $742.69 | +3.1% |
| Cardano (ADA) | $0.205 | -8.0% |
| Dogecoin (DOGE) | $0.0777 | -3.2% |
| Hyperliquid (HYPE) | $76.57 | -4.0% |
Bitcoin ETFs attracted net inflows during the week, although substantial withdrawals occurred Thursday and Friday. Ethereum ETFs experienced continued net outflows.
Institutional adoption nevertheless continues to expand, particularly in stablecoin payments, digital asset custody, and tokenized financial products.
My preference remains Bitcoin until broader cryptocurrency market participation improves.
Key Market Drivers
1. AI infrastructure spending faces increasing scrutiny
Meta increased its expected annual capital spending range to approximately $135–$145 billion, raising concerns about financing, profitability, and the returns on AI investment.
Investors are increasingly distinguishing between financially strong infrastructure suppliers and companies dependent on large future financing commitments.
I continue to favor established suppliers of electrical equipment, cooling, power generation, and networking infrastructure.
2. Oil prices create additional inflation risks
Brent crude finished above $116 per barrel as geopolitical tensions and supply disruptions intensified.
Higher energy costs could pressure consumer spending, business margins, and Federal Reserve policy.
Oil remains one of the most important indicators to monitor during the remainder of the fourth quarter.
3. Housing remains under pressure
September housing starts declined approximately 5.2%, while October homebuilder confidence fell to 29.
Elevated mortgage rates and affordability concerns continue to affect housing demand.
4. Business activity remains resilient
Preliminary October manufacturing and services PMI readings indicated continued economic expansion.
The strength in business activity is encouraging, but persistent cost pressures complicate the inflation outlook.
5. Consumer confidence remains weak
The final October University of Michigan Consumer Sentiment Index registered 48.0, reflecting continued concerns about affordability and inflation.
Elevated energy prices could place additional pressure on household purchasing power.
6. Federal Reserve policy remains uncertain
The federal funds target range remains 3.75%–4.00%.
Markets generally expect no rate change at the October 27–28 meeting, but investors will focus on guidance regarding future increases and the inflation outlook.
7. Corporate earnings become the next major catalyst
Microsoft, Alphabet, and Amazon report during the coming week.
Their results will provide important evidence about cloud demand, AI infrastructure spending, revenue growth, and profitability.
Stronger earnings could stabilize technology shares, while disappointing guidance could extend the correction.
Emerging Crypto Projects & Ecosystem News
JPMorgan expands JPM Coin to Ethereum
JPMorgan’s institutional deposit token is now available on Ethereum, expanding the use of public blockchain infrastructure for institutional settlement.
HSBC launches a stablecoin
HSBC introduced RedCoin, a regulated Hong Kong dollar stablecoin available through its PayMe platform, with more than 3.3 million users eligible for access.
U.S. stablecoin regulations advance
The OCC finalized rules implementing the GENIUS Act, effective January 18, 2027, establishing a clearer regulatory framework for payment stablecoins.
Tokenized equities encounter resistance
Twenty-two public companies have objected to proposed tokenized trading of their shares on OKXICE, demonstrating that regulatory compliance and issuer acceptance remain important challenges.
These developments reinforce my view that blockchain is becoming increasingly integrated into mainstream financial infrastructure, even as cryptocurrency prices remain volatile.
Outlook for the Week Ahead
The week of October 26–30 includes several major economic releases and corporate earnings reports.
Monday, October 26
Chicago Fed National Activity Index and Dallas Fed manufacturing survey. Verizon earnings.
Tuesday, October 27
September durable goods orders, October consumer confidence, and September new home sales.
The Federal Reserve begins its two-day meeting.
Earnings include Boeing, Coca-Cola, Visa, and SoFi.
Wednesday, October 28
Federal Reserve interest-rate decision — 2:00 p.m. Eastern.
Earnings include Microsoft and Alphabet, making this a particularly important session for technology and AI investment.
Thursday, October 29
Third-quarter GDP and September PCE inflation — 8:30 a.m. Eastern.
Weekly unemployment claims are also scheduled.
Earnings include Amazon, Eli Lilly, and Mastercard.
Friday, October 30
Third-quarter Employment Cost Index and October Chicago PMI.
Earnings include ExxonMobil and AbbVie.
What I Am Watching: The combination of the Fed decision, inflation, GDP, and major technology earnings could create substantial volatility.
Strong earnings and stable inflation expectations would support a recovery, while weaker AI guidance or additional inflation pressure could extend the recent correction.
Key Levels to Watch
| Market | Current Level | Upside Reference | Downside Reference |
|---|---|---|---|
| S&P 500 | 7,623.68 | 7,700 / 7,800 | 7,600 / 7,500 |
| Nasdaq Composite | 25,955.34 | 26,500 / 27,000 | 25,500 / 25,000 |
| Dow Jones | 52,215.16 | 52,500 / 53,000 | 51,500 / 51,000 |
| Gold | $4,007.90 | $4,100 / $4,200 | $4,000 / $3,950 |
| Silver | $53.95 | $56 / $58 | $52 / $50 |
| WTI Crude | $103.27 | $105 / $110 | $100 / $95 |
| Bitcoin | $80,525 | $84,000 / $85,000 | $80,000 / $78,000 |
| Ethereum | $2,340 | $2,500 / $2,600 | $2,300 / $2,200 |
| Solana | $101.27 | $110 / $120 | $100 / $95 |
These are reference levels for assessing future price behavior, not guaranteed technical turning points.
As always, stay informed and adjust your strategies based on the evolving market conditions. All trades are posted on our Private Twitter Feed for subscribers and are included in the track record posted below under Completed Trades. I am currently trading 15 lots given the account balance and will adjust as necessary based on market developments.
Trading futures contracts and commodity options involves substantial risk of loss, and may not be appropriate for all investors. Past performance is no guarantee of future results. Please see our Disclaimer for more information.
The trades below are discussed on the Daily Update: – Click Here for a FREE Trial
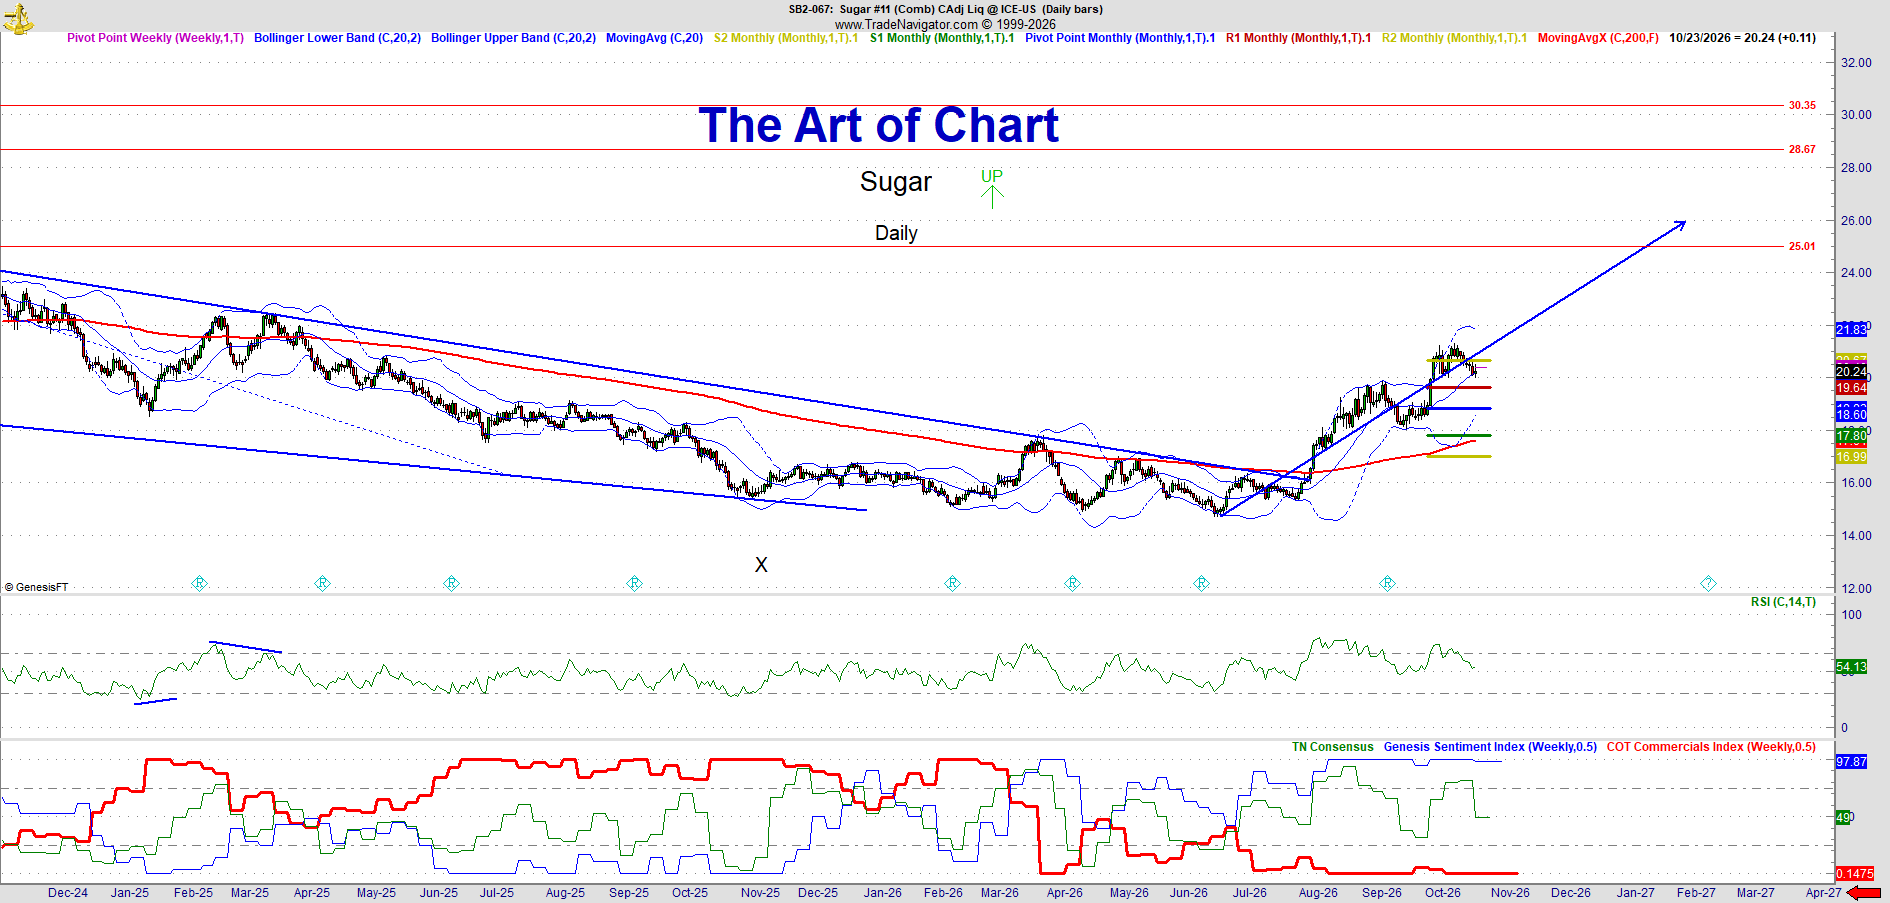
Sugar
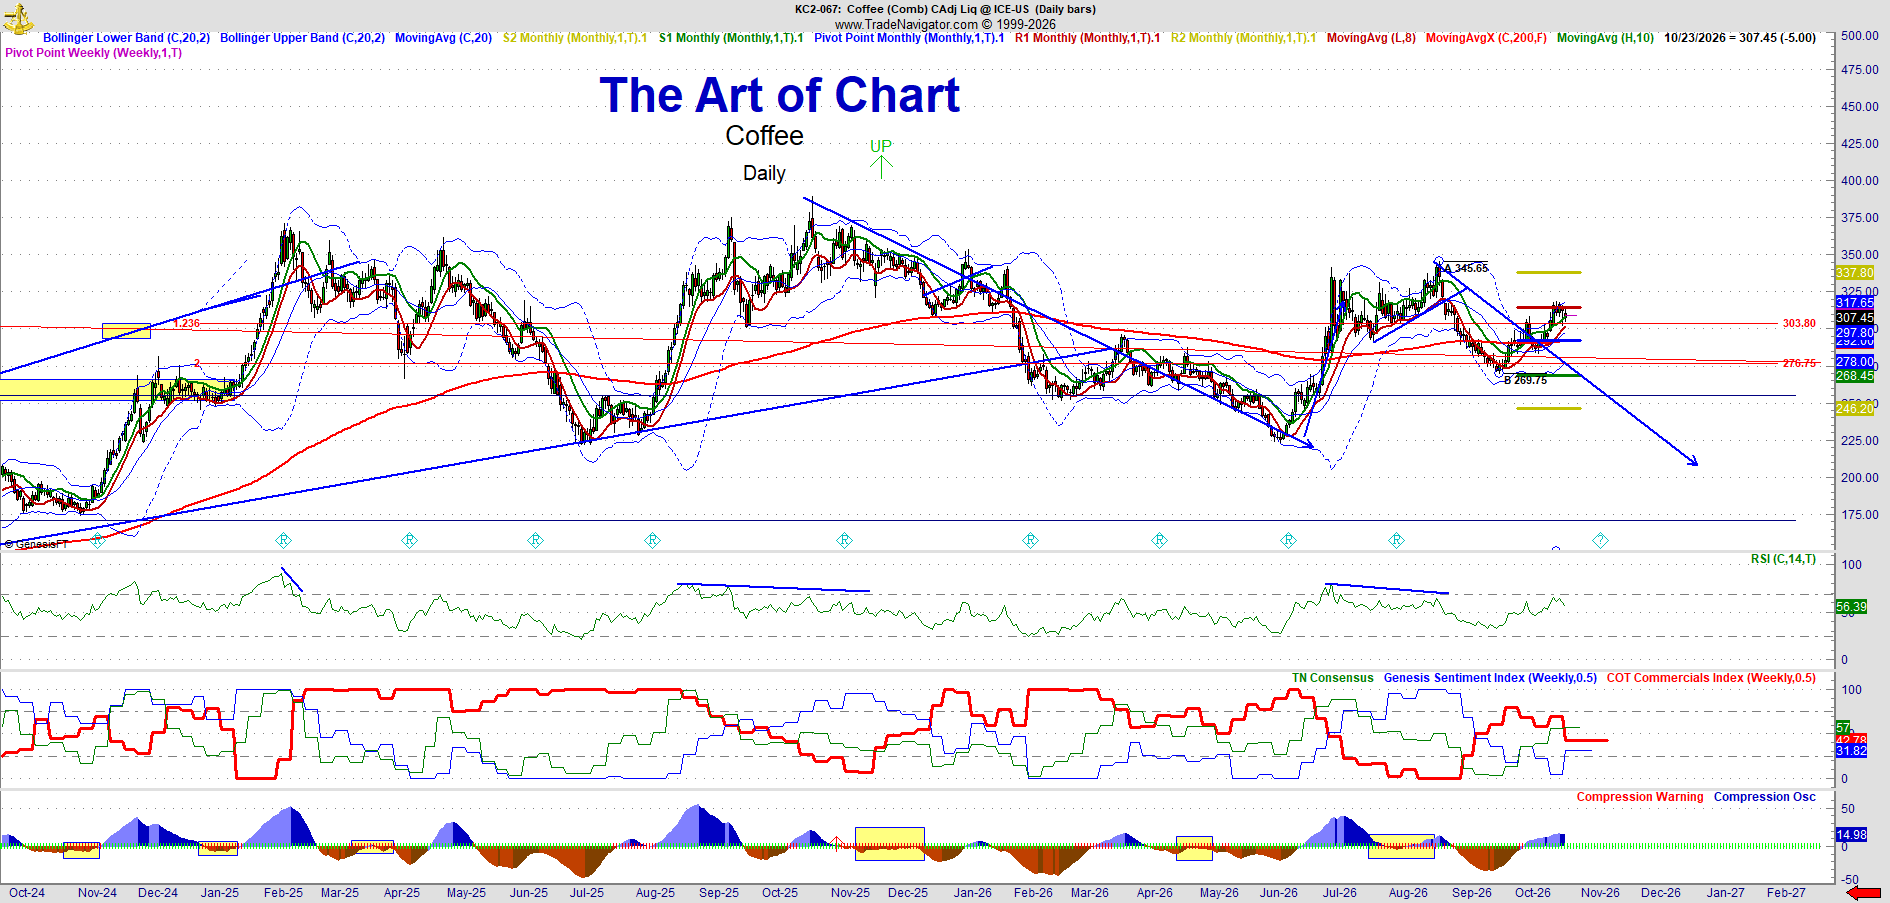
Coffee
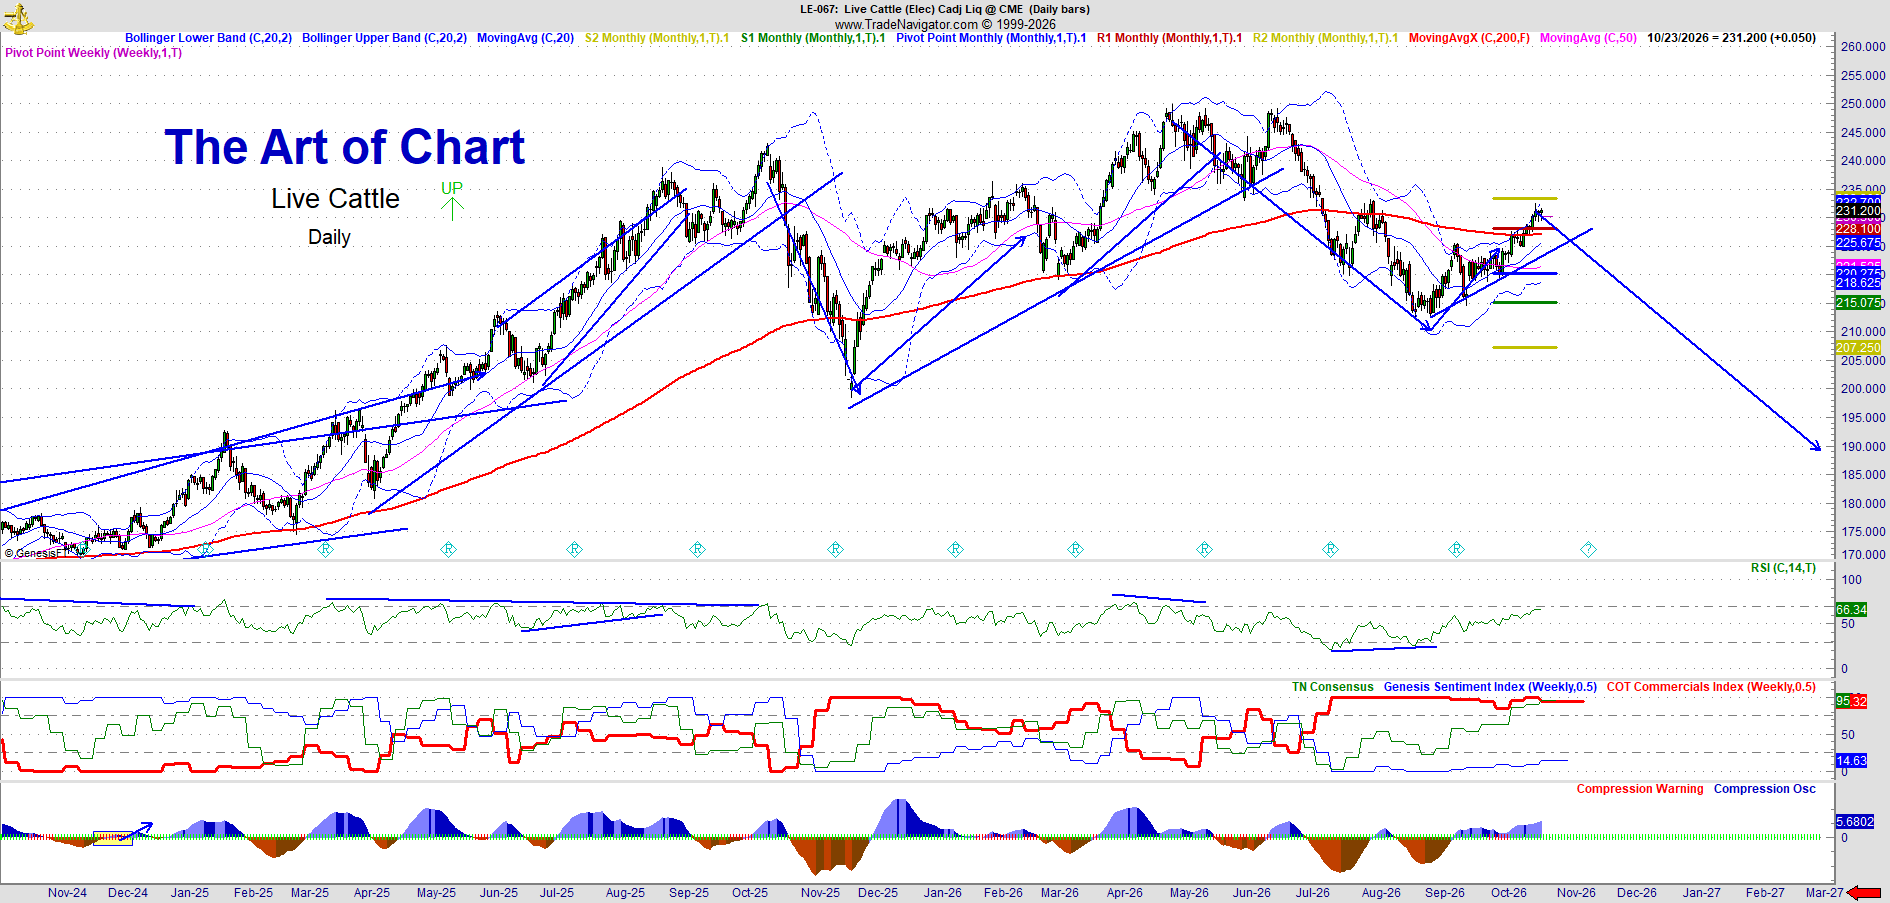
Live Cattle
Gold (GC)
Come see what we are trading – Try our 30 day FREE trial – Click Here
COMPLETED TRADES
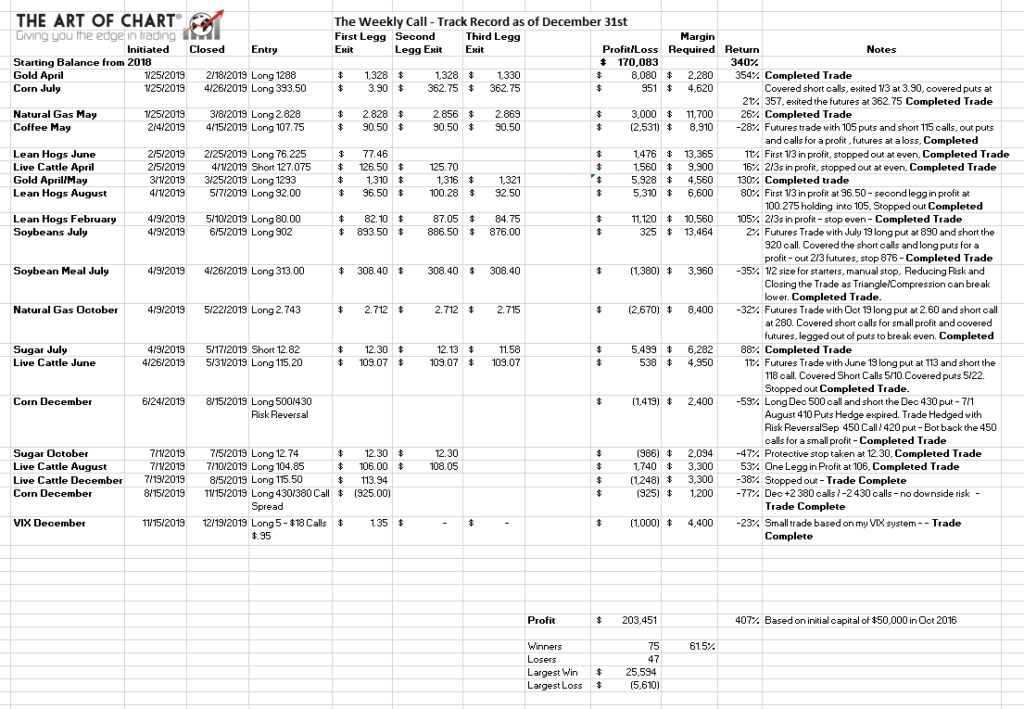
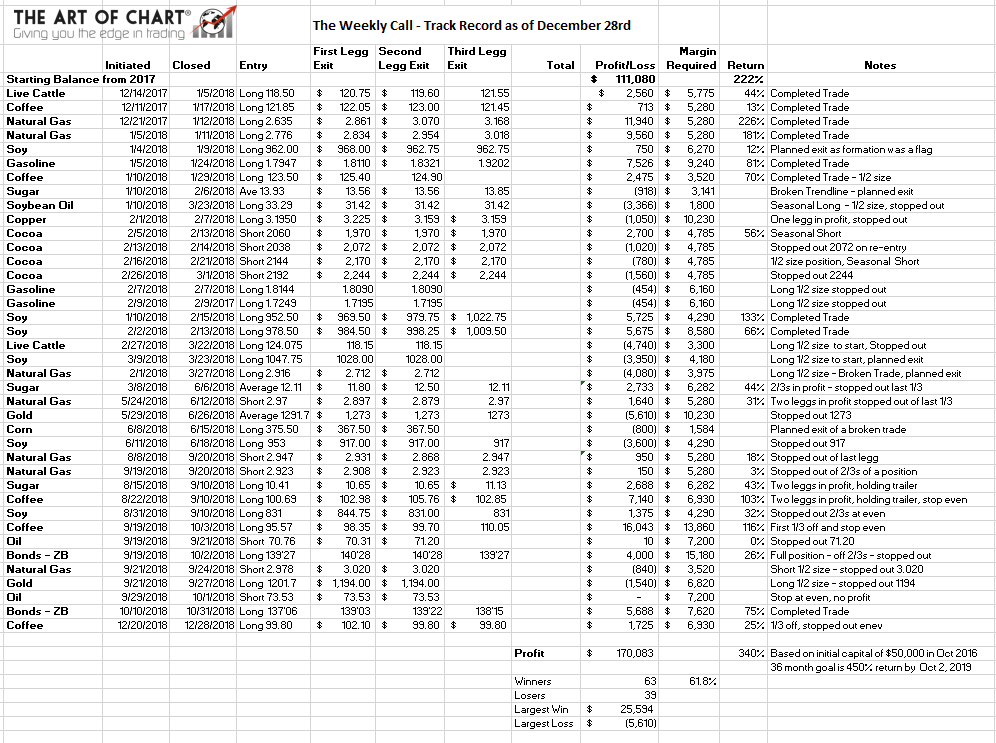
Track Record of Completed Trades
The purpose of this blog is to demonstrate how to swing trade futures using our methodology to select high-quality setups and manage the trade with our risk management approach. This track record is based on entries and exits as posted in this blog. I am currently using 15 lots for the Striker trades which is based on this account being over $375,000. Each lot for auto trading at Striker requires $25,000 per lot. See the videos below for more information.
Track Record January 2022 thru December 2022 Click Here.
Track Record January 2021 thru December 2021 Click Here.
Track Record January 2020 thru December 2020 Click Here.
Track Record January 2019 thru December 2019 Click Here.
Track Record January 2018 thru December 2018 Click Here.
Track Record October 2016 – December 2017 Click Here.
*** Trading futures contracts and futures options involves substantial risk of loss, and may not be appropriate for all investors. By reading this web site, you acknowledge and accept that all trading decisions are your sole responsibility. Trading strategies referenced on this web site and associated documents and emails are only suggestions, no representation is being made that they will achieve profits or losses. Past performance is no guarantee of future results.. See our disclaimer here.
Completed trade in Cattle as of November 28th
We expect subscribers to have captured 60% of the swing in live cattle which is over $14,500 in profit using a margin of only $5,115. A great example of using leverage in futures.
Completed Trade in Coffee as of December 12th
The total swing was $37.00 and we expect subscribers to have captured 60% of a wing or $22 in coffee for a profit of over $25,500 using a margin of $8,850. A great example of using leverage in futures. See the video below for the review of the trade.
Completed Trade in Natural Gas as of January 2nd
We were stopped out of out last 1/3 position as weather-related news created a gap down on January 2nd and a possible flat with support at 3.196. This concludes our trade with natural gas; we exit with 550 ticks on 2/3s of a position with $8,500 in profit.
Completed Trade in Coffee as of January 19th
We exited the coffee trade on January 19th with $17 or over $15,000 in profit using a margin of $8,850. A great example of using leverage in futures.
Completed Trade in Gold as of February 8th
We exited the gold trade on February 8th with over $14,000 in profit. We entered on January 3rd and held the trade into the high window. We will re-enter gold in a few weeks after a backtest.
 25th Oct 2026